UK Junior ISAs & Junior SIPPs
I'm not giving my children a head start. I'm giving them a different starting line entirely.
Two accounts most parents never use properly. See what they could build for your child — in 60 seconds.
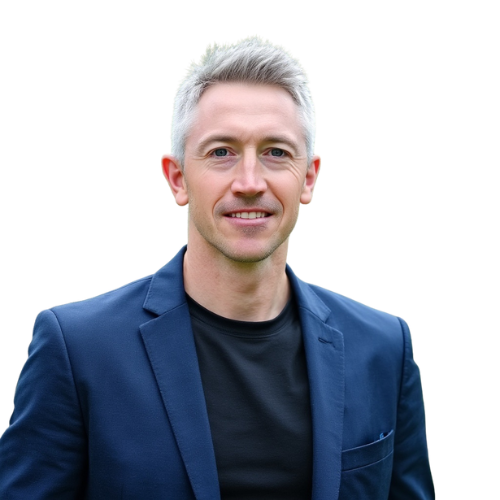
Marc, dad of two, near Southam. The figures about my own accounts come from my statements.
Free to use. No signup.
£42,369 into Junior ISAs and Junior SIPPs for my two children since 2015. The government added £4,305. It's worth £80,830 today — and I made one £20,000 mistake along the way.
The thing nobody tells you
Put in £2,880. Your child gets £3,600.
You pay in
£2,880
Your child gets
£3,600
That's not a projection. It's what happens the moment you contribute to a Junior SIPP — the government adds 20% in tax relief, automatically, before a single fund has moved.
Most parents have never heard of a Junior SIPP. Most have heard of a Junior ISA, usually from a bank offering a cash account paying 2%.
The two do different jobs. The Junior ISA is money your child can reach at 18. The Junior SIPP compounds quietly for five decades and gets topped up along the way.
You don't have to choose.
The quiet cost of waiting
Most parents do the sensible thing — open a cash account, add the birthday money, watch it lose slowly to inflation.
Over eighteen years that gap is often the difference between a deposit and something life-changing.
And the biggest lever isn't how much you put in. It's how long it compounds. Starting five years earlier usually beats doubling the amount later — and five years is the one thing you can never buy back.
The calculator
See what a head start is really worth
Move the sliders. Watch what happens when you give your child time instead of just money.
One slider matters more than the rest: contribute until age. Drag it back and watch what four decades of compounding does with nothing further from you. That's my own story — I stopped contributing years ago and the accounts kept growing.
Projected combined value
£492,578
In 54 years, when your child turns 57 — from £18,000 of your own money at 7% a year.
Junior ISA
Junior SIPP
That's £2,250 the government added — before it's even started growing.
This number assumes you leave it alone. I didn't.
In 2022 I sold to cash and it cost my children about £20,000. Every Thursday at 7am I send one idea about investing for children, with real numbers, including what I got wrong.
Your card, as it will download
- A shareable card with your child's projection, the ISA and SIPP split and the government top-up
- I'm not an adviser and take no commission. Unsubscribe in a click.
I read every reply.
This tool is for illustration only and doesn't constitute financial advice. Growth rates aren't guaranteed and past performance isn't a reliable guide to the future. Always consider speaking to a regulated financial adviser before making investment decisions.
Who's writing this
“I put £42,369 into Junior ISAs and Junior SIPPs for my two children over ten and a half years. It's worth £80,830 today. No adviser.
Then in 2022 I did the thing I now teach people never to do. I sold everything to cash, certain the market would fall. It didn't. I bought back 30% higher. That cost my children around £20,000.
I'm not a financial adviser and I'll never tell you what to buy. But I can explain how these accounts work, what the government adds, and what it costs to try to outsmart a market. I know that last one properly.”
— Marc, The Compound Parent
This is financial education, not financial advice. Past performance is not a guide to future performance.
Know a parent who's never heard of a Junior SIPP?
Most haven't. Send them the calculator — it takes two minutes and the government top-up does the rest.